10 Realistic Ways to Increase Your Income When Your Budget Has Nothing Left to Cut
 Eslee
You've canceled subscriptions.
You're cooking at home more often.
You're watching your grocery spending.
You've reduced unnecessary shopping.
You're comparing prices before you buy.
And you've already gone through your budget looking for expenses you can eliminate.
Yet when you look at the numbers, you realize something frustrating:
There's almost nothing left to cut.
This is where a lot of traditional budgeting advice can become difficult to follow.
“Spend less” sounds simple until most of your paycheck is already going toward necessities.
You still need somewhere to live.
You need food.
Transportation.
Utilities.
Insurance.
Healthcare.
And all the other expenses that come with everyday life.
There comes a point when constantly looking for another $5 or $10 to cut isn't going to solve a larger income problem.
When you've carefully reviewed your spending and your essential expenses are still consuming most of what you earn, it may be time to stop asking:
“What else can I cut?”
and start asking:
“How can I increase my income?”
That doesn't mean you need to quit your job, work every waking hour, or build a six-figure business.
An additional $100, $300, or $500 a month could begin creating the financial breathing room you've been looking for.
The goal is to find a realistic way to increase your income that fits your skills, available time, responsibilities, and financial goals.
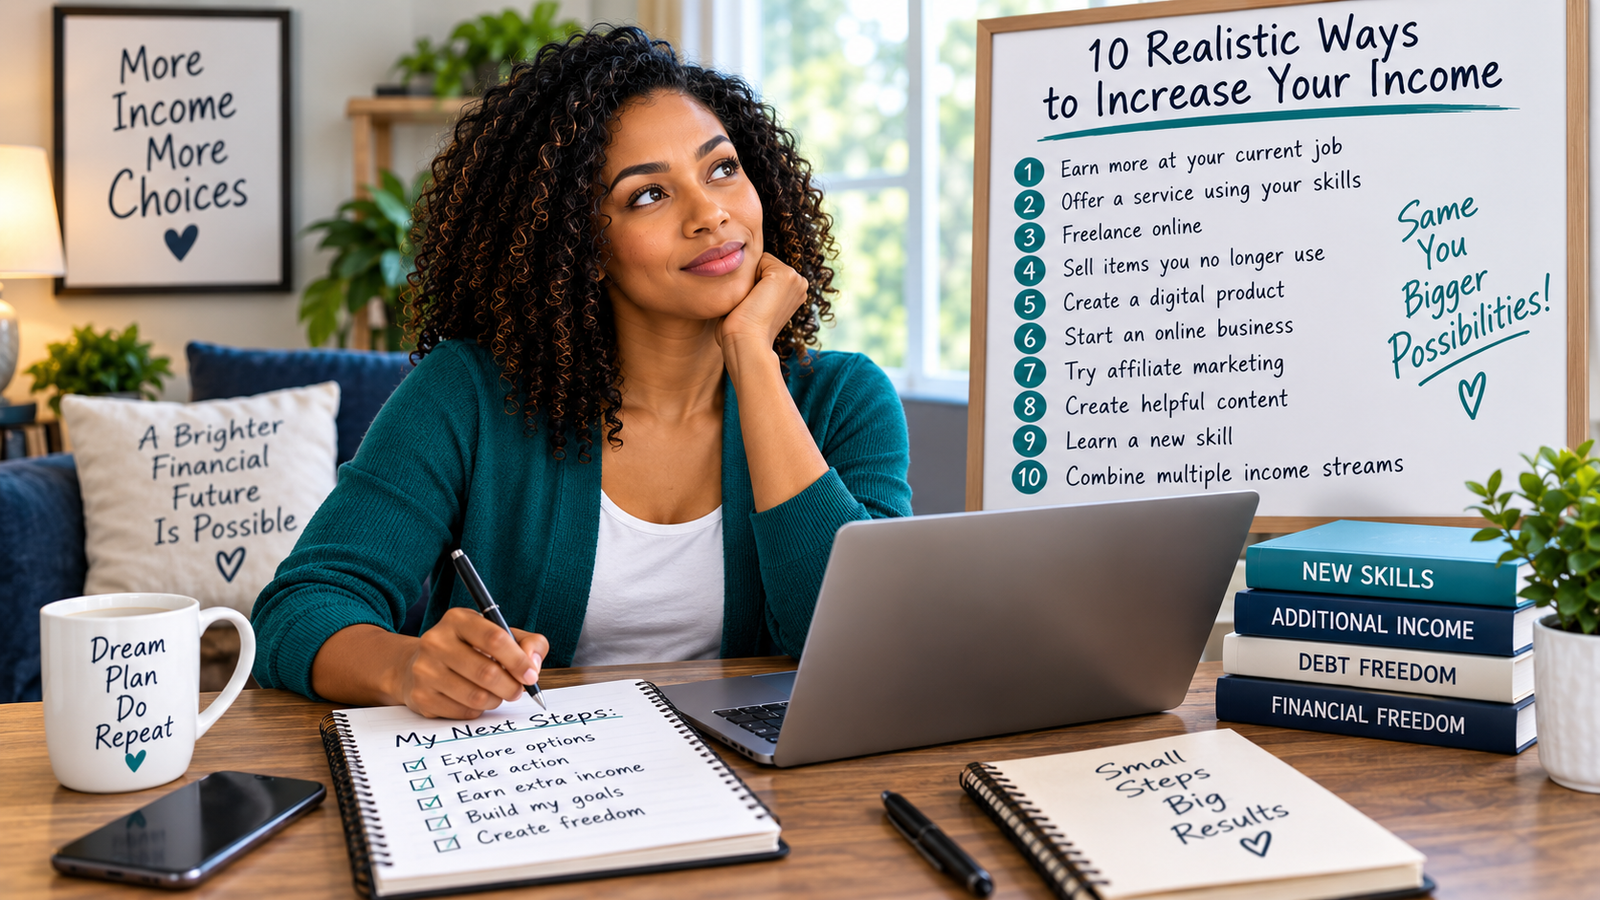
Here are 10 possibilities to consider.
First, Decide What You Want the Extra Income to Do
Before you start earning more money, decide what that money is supposed to accomplish.
This is important because additional income can disappear just as easily as your regular income.
Suppose you begin earning an additional
$400 per month.
At first, that sounds like a significant improvement.
But gradually you start eating out more.
You shop a little more.
You add a new subscription.
Maybe you'll upgrade something you've been wanting.
A few months later, you're earning $400 more but don't feel any further ahead.
Your income increased.
But your lifestyle increased right along with it.
That's why additional income needs a purpose.
For example, you might decide:
$150 → emergency savings
$150 → debt payoff
$50 → upcoming expenses
$50 → something you enjoy
Your numbers may look completely different.
That's okay.
The important thing is to decide what you want the extra money to accomplish before it arrives.
Now let's look at ways you might earn it.
1. Look for Ways to Earn More at Your Current Job
Before starting something completely new, look at the income source you already have.
Your job.
Could you:
- Work occasional overtime?
- Pick up additional shifts?
- Take on responsibilities that qualify for higher pay?
- Apply for an internal promotion?
- Move into a better-paying department?
- Ask for a compensation review?
Sometimes people immediately begin searching for side hustles while overlooking opportunities available through their current employer.
Suppose working a few additional hours each month brings in another $200.
If those hours fit your schedule, that may be easier than starting an entirely new business from scratch.
But don't only ask:
“How can I work more hours?”
Also ask:
“How can I make my current hours more valuable?”
That's an important difference.
Working more hours may increase your income temporarily.
Increasing your hourly rate or salary can improve your income without requiring you to continually give up more of your time.
2. Turn a Skill You Already Have Into a Service
You probably know how to do something that another person or business would pay to have done.
And it doesn't have to be an unusual skill.
Think about what people already ask you for help with.
Maybe you're good at:
- Writing,
- Proofreading,
- Organizing,
- Bookkeeping,
- Graphic Design,
- Social media,
- Administrative work,
- Spreadsheets,
- Photography,
- Video editing,
- Tutoring,
- Cleaning,
- Pet care,
- Lawn care,
- or Technology.
Instead of asking:
“What's the perfect side hustle?”
Ask:
“What problem can I already solve for someone?”
That's often a much easier place to begin.
For example, someone who is organized and comfortable with administrative work might offer virtual assistant services.
Someone who writes well might offer blog writing or proofreading.
Someone who understands bookkeeping might help a small business organize its records.
Someone who enjoys designing graphics might create social media content for local businesses.
You don't have to offer 20 different services.
Start with one service that solves one problem for one type of customer.
Keep the Beginning Simple
You don't need an expensive website, complicated branding, or several paid subscriptions to get started.
First, answer four questions:
What am I offering?
Who needs it?
What problem does it solve?
What will I charge?
Then concentrate on finding your first customer.
You can improve the business as you learn.
3. Freelance Online
Freelancing can be especially useful if you need something flexible enough to work around your existing job or family responsibilities.
Depending on your skills, freelance work could include:
- Content writing,
- Editing,
- Virtual assistance,
- Graphic design,
- Research,
- Bookkeeping,
- Web design,
- Video editing,
- Social media management,
- Customer support,
- or Consulting.
One mistake beginners sometimes make is offering too many things.
A focused service is easier for potential customers to understand.
Instead of saying:
“I do online work.”
You could say:
“I write SEO-friendly blog posts for small businesses.”
Instead of:
“I help businesses.”
You might say:
“I help small business owners organize their monthly bookkeeping.”
Specificity helps people understand exactly why they might hire you.
Don't Spend Too Much Before You Earn Anything
This is especially important when you're trying to increase your income because your budget is already tight.
You don't need to buy every tool available before you've earned your first dollar.
Start with what you genuinely need.
As money begins coming in, you can decide whether investing in additional tools will help you work faster, produce better results, or serve more customers.
The goal is to create income, not another category of expenses.
4. Sell Things You No Longer Use
This isn't a permanent income strategy, but it can provide immediate financial breathing room.
Look around your home.
You may have:
- Electronics,
- Furniture,
- Clothing,
- Tools,
- Collectibles,
- Unused appliances,
- Exercise equipment,
- Children's items,
- Or hobby supplies
that still have value.
Suppose you sell several unused items and make:
$600.
Before the money arrives, decide what you'll do with it.
For example:
- $300 → emergency savings
- $200 → debt
- $100 → upcoming expenses
Now something that was taking up space has helped improve your financial situation.
Selling unused belongings can also teach you basic business skills.
You learn how to:
- Take clear photographs.
- Write descriptions.
- Set prices,
- Communicate with buyers,
- Negotiate,
and understand what people are willing to pay for.
Those skills can become useful if you eventually decide to sell products regularly.
5. Create a Simple Digital Product
If you have knowledge that can help someone solve a problem, you might consider turning it into a simple digital product.
Digital products can include:
- Checklists,
- Planners,
- Templates,
- Spreadsheets,
- Workbooks,
- Guides,
- Printable resources,
- Journals,
- Or educational materials.
The key is to start small.
You don't need to begin by creating a massive course or a 200-page book.
Identify one problem and create something that helps solve it.
For example, instead of creating:
“The Complete Guide to Organizing Your Entire Life”
You could create:
“The 15-Minute Weekly Home Organization Checklist.”
The second idea solves a smaller, clearer problem.
And that can make it easier for a potential customer to understand exactly what they're getting.
Validate the Idea Before Spending Weeks Creating It
Before investing a large amount of time, ask:
- Are people actually looking for help with this problem?
- Who would use this product?
- What would make it valuable enough to purchase?
- Where would potential customers find it?
Creating the product is only one part of selling online.
You also need to think about how people will discover it.
Your first product may not immediately produce significant income.
That's okay.
You're also learning what people want and how online selling works.
6. Start a Small Online Business
If you're looking for something with longer-term potential, you may eventually consider building an online business.
An online business can take many forms.
You might:
sell physical products,
sell digital products,
offer services,
create educational content,
build an audience,
or combine several income methods.
But it's important to remember:
An online business is still a business.
Putting something online doesn't automatically make people buy it.
You still need to understand:
who you're helping,
What problem are you solving?
what you're offering,
where your customers are,
and why they should choose your product or service.
Think Beyond the Product
A basic online business might look something like this:
Helpful content
↓
People discover you.
↓
They begin trusting your information.
↓
You present a useful product or service.
↓
Some become customers.
↓
You learn from their feedback.
↓
You improve.
This is one reason online businesses can take time to grow.
You aren't simply creating something.
You're also learning how to attract and serve an audience.
Start small enough that you can afford to learn.
7. Explore Affiliate Marketing
Affiliate marketing is another way some content creators generate additional income.
The basic concept is straightforward.
You recommend a product or service you believe could help your audience.
If someone purchases through your referral, you may receive a commission.
Affiliate marketing can work alongside:
- Blogging,
- YouTube,
- Pinterest,
- Email newsletters,
- Social media,
- Tutorials,
- Reviews,
- Or educational content.
But simply placing links into content doesn't automatically create income.
The recommendation needs to make sense.
Think about it this way:
Problem → Helpful information → Possible solution
Suppose you're teaching someone how to organize their finances.
A relevant recommendation might be something that helps them budget, organize, track goals, or complete another task connected to the problem they're trying to solve.
The recommendation should feel like a natural extension of the information—not a random product placed into the article.
Protect Your Reader's Trust
Before recommending something, ask:
Would I feel comfortable telling someone I care about to consider this?
Does it actually relate to the problem I'm discussing?
Do I understand what the product does?
Can I explain who it may—and may not—be appropriate for?
Trust is far more valuable than one commission.
If you're building a long-term blog or audience, protecting that trust matters.
8. Create Helpful Content Around Something You Know
You don't necessarily need to be the world's leading expert to create useful content.
You can create content around your knowledge, experience, research, or something you're actively learning.
Maybe you understand:
- Budgeting,
- Saving money,
- Organization,
- Gardening,
- Cooking,
- Technology,
- Career development,
- Home improvement,
or another subject people regularly search for.
Content might include:
- blog posts,
- YouTube videos,
- Pinterest content,
- newsletters,
- tutorials,
- or social media posts.
Content itself doesn't automatically generate income.
But over time, it can become the foundation for different income opportunities.
For example, content can help people discover:
your services,
your products,
your recommendations,
or your business.
Solve Problems Instead of Simply Talking About Topics
Compare these two titles:
“My Thoughts About Budgeting”
and
“How to Create a Budget When Your Income Changes Every Month.”
The second addresses a specific problem.
That's important.
When someone searches online, they're often looking for an answer.
Create content that helps provide one.
The more clearly you understand your reader's problem, the easier it becomes to create something useful.
9. Learn One Skill That Could Increase Your Earning Potential
Sometimes the best way to increase your income isn't to immediately start another job.
It may be to increase the value of your skills.
Depending on your interests and career, useful skills might include:
- bookkeeping,
- copywriting,
- SEO,
- digital marketing,
- sales,
- web design,
- data analysis,
- project management,
- video editing,
- automation,
- or another specialized skill.
But there's an important warning here.
Don't confuse buying courses with increasing your income.
Learning becomes financially useful when you actually apply the skill.
Before spending money on training, ask:
What skill am I learning?
Who pays people for this skill?
How could I use it to earn more?
How long might it realistically take me to become competent?
Can I practice the skill before making a large financial investment?
You don't need to collect certificates.
You need skills you can actually use.
The goal is:
Learn → Practice → Apply → Earn
10. Combine Several Small Sources of Additional Income
You don't necessarily need one opportunity that immediately generates $1,000 per month.
You might eventually reach that goal through several smaller sources.
For example:
Freelance work: $300
Selling unused items: $150
Digital product sales: $100
Occasional overtime: $200
Other income: $75
Total: $825
Not every month will look the same.
Some income sources may grow.
Others may stop working.
Eventually, you may decide to focus more heavily on the one showing the most potential.
Experimenting can help you discover what works best with:
your skills,
your schedule,
your responsibilities,
and the amount of time you're willing to commit.
Don't Let the Cost of Making Money Keep You Broke
This is one of the most important parts of increasing your income.
It's surprisingly easy to spend a lot of money trying to make money.
- Courses.
- Software.
- Subscriptions.
- Equipment.
- Websites.
- Advertising.
- Business memberships.
Some of these expenses may eventually be useful.
But remember why you started.
You wanted more financial breathing room.
Suppose your side business brings in:
$500 per month.
But it costs:
$350 per month
to operate.
You haven't created $500 of additional income.
Before considering taxes, you've created approximately:
$150 in profit.
That's why you need to understand three basic numbers.
Revenue
How much money did the activity bring in?
Expenses
How much did it cost you to generate that revenue?
Profit
How much is left after the business expenses?
Revenue can make an opportunity look exciting.
Profit tells you whether it's actually improving your finances.
Be Careful With Easy-Money Promises
When your budget is already stretched, the idea of making money quickly can be especially appealing.
That's also when you need to be careful.
Be cautious when an opportunity suggests that:
You'll earn large amounts almost immediately.
Little effort is required.
Results are practically guaranteed.
You don't need to understand how the business works.
Or you need to spend money immediately because the opportunity may disappear.
Ask practical questions instead.
What exactly will I be doing?
What am I selling?
Who is paying me?
Why are they paying me?
What are the total costs?
What skills do I need?
How will customers find me?
How long might it take before I earn anything?
What happens if I don't make money immediately?
A legitimate income opportunity should make sense when you examine how the money is actually generated.
You don't need a miracle.
You need something you can understand, test, and realistically sustain.
What Should You Do With the Additional Income?
Let's imagine you've found a way to consistently bring in:
$500 more per month.
That's where your earlier budgeting work becomes important.
If that entire $500 automatically becomes additional spending, your finances may not improve much.
Instead, you could divide it intentionally.
For example:
$200 → emergency savings
$175 → debt
$75 → sinking funds
$50 → enjoyment
Over 12 months, assuming the additional income remained consistent, that could mean:
$2,400 toward emergency savings
$2,100 toward debt
$900 toward upcoming expenses
and
$600 is intentionally available for enjoyment.
That's:
$6,000 of additional annual income
being used intentionally.
Now you're not simply earning more.
You're using your additional income to change your financial position.
Your First Goal Doesn't Have to Be $1,000 a Month
It's easy to become impressed by large income claims online.
Someone made $5,000.
Someone else made $10,000.
Another person says they replaced their salary.
Those stories can make your first $50 feel insignificant.
It isn't.
If you're starting from zero, try thinking in stages.
First goal: Earn $50.
Then:
Earn $100.
Then:
Earn $250 consistently.
Then perhaps:
Reach $500.
Your first dollars are valuable for another reason.
They provide information.
If you're freelancing, you learn whether someone will pay for your service.
If you're selling products, you learn whether people want them.
If you're creating content, you learn what attracts attention.
If you're building an online business, you begin learning how visitors become customers.
Don't underestimate the importance of your first small result.
It's proof that something happened outside your plan.
A real person paid you.
Then you can ask:
How can I do that again?
Choose One Income Experiment
After reading 10 possibilities, you may be tempted to try several of them at once.
That can quickly become overwhelming.
Instead, choose one idea and test it.
For example:
“For the next 30 days, I'll try to earn my first $100 through freelance writing.”
Or:
“I'll list 10 unused items for sale.”
Or:
“I'll research opportunities for additional income at my current job.”
Or:
“I'll create one simple digital product and test whether people are interested.”
Or:
“I'll publish four useful pieces of content answering questions people are searching for.”
Then evaluate the experiment.
Ask:
Did I make any money?
What worked?
What didn't?
What took more time than expected?
Did I enjoy doing it?
Is there evidence that this could grow?
What would I do differently next time?
Then decide whether to continue, adjust, or try something else.
You don't need to know exactly what your long-term income strategy will be before you start.
Sometimes you discover it by experimenting.
When There's Nothing Left to Cut, Create More Possibilities
Cutting unnecessary expenses is an important part of money management.
If you're paying for things you don't use or spending money without realizing it, finding those leaks can create valuable breathing room.
But cutting expenses has a limit.
You still need somewhere to live.
You still need food.
Transportation.
Utilities.
Insurance.
And you shouldn't have to eliminate every enjoyable thing from your life just to make your finances work.
Eventually, the next step may not be another cut.
It may be more income.
Maybe your first goal is an additional $100 per month.
Then $250.
Then $500.
That money helps you build a buffer.
You rely less on credit cards.
Your emergency savings begin growing.
You start paying down debt.
An irregular expense arrives, and this time you have money set aside.
Eventually, additional income may do more than help you get through the month.
It can help you build something for the future.
A larger emergency fund.
A debt-free life.
A new skill.
A small business.
More savings.
Or simply more choices.
That's the real purpose of increasing your income.
Not just to have more money to spend, but to create more room to build the financial life you want.